A Reflection
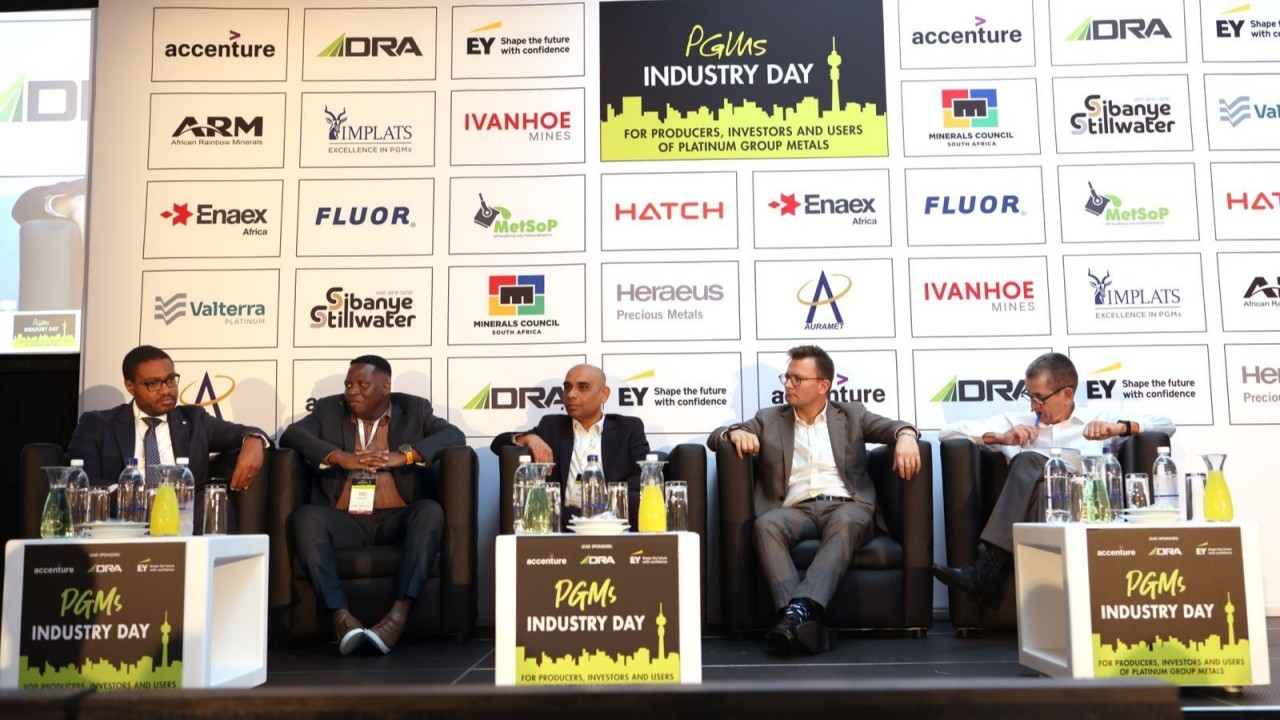
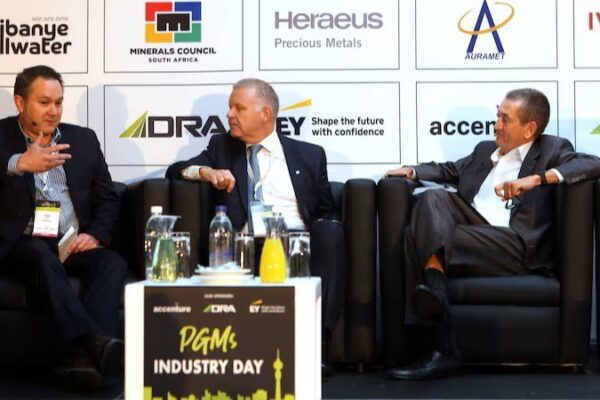
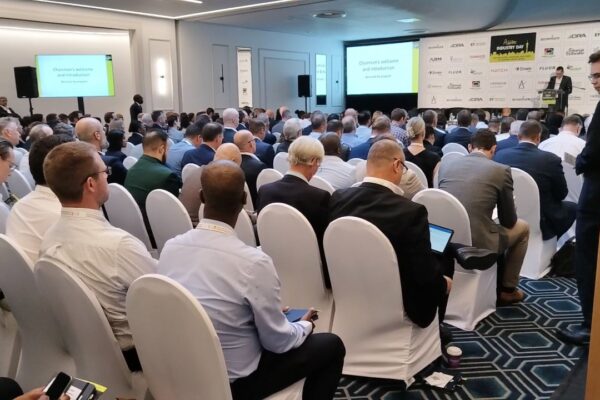
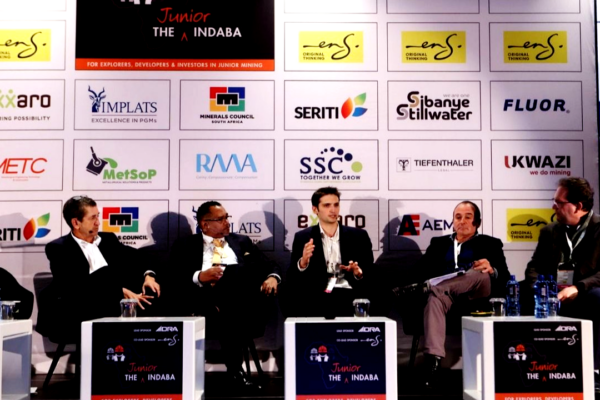
There are conferences where people attend because they have to. And then there are days like this year’s
Resources for Africa
PGM Day, where people attend because they want to.
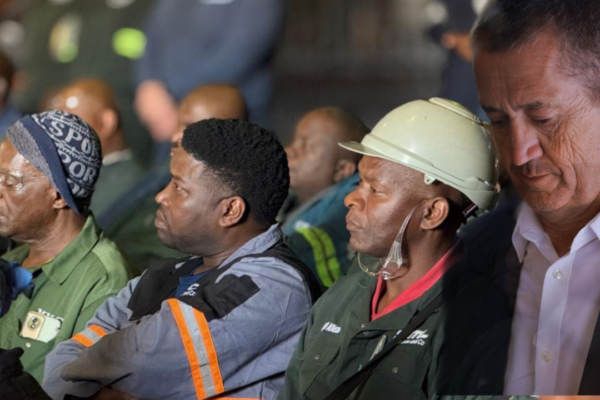
The difference shows. High attendance, engaging discussions and, perhaps most importantly, a room that was willing to listen as much as it spoke. That, in itself, is usually a sign that something in the industry is shifting. However, in the very same breath, some things in the industry remain the same.
If one compares the tone to a year ago, the change is unmistakable. Last year, the mood was defensive, the green shoots of a price recovery were completely overshadowed by the first of Trump’s Executive Order Tariff announcements, and we didn’t know about TACO yet!
This year, it was pragmatic, confident, and had just a hint of cautious optimism. Whilst of course the Middle East is hanging like a dark oil fire cloud over the world’s economy, we couldn’t quite call it an air of exuberance. Not yet. The atmosphere had the kind of confidence that comes from having survived a difficult period, but hope from the beginnings of some sort of structural return to the market.
The major producers, in particular, struck a consistent note: disciplined, measured, and not rushing back into growth for the sake of it. There was a clear sense that the industry remembers what happens when capital discipline disappears at the top of the cycle.
One of the more interesting dynamics was the contrast between producers and project developers. The producers spoke the language of balance sheets, margins, and sustainability, whilst the developers brought optimism!
Because project developers don’t have the luxury of caution, they need capital, momentum, and a narrative that justifies both. That tension between caution and conviction is healthy, because the industry needs both.
For all the differences of opinion in the room, there was one area where we were mostly aligned: confidence in platinum is returning and it is not being matched by palladium. Platinum is increasingly seen as structurally supported, relevant across multiple demand streams, and central to future technologies. Palladium, by contrast, carries more uncertainty.
For years, hydrogen has been the industry’s favourite future promise.
What felt different this time was not the volume of discussion, but the credibility of it. The inclusion of hydrogen in China’s five-year plan is significant, hydrogen is not yet dominant, but it is no longer theoretical. By elevating hydrogen from a perennial “future promise” to a sovereign industrial mandate, China has replaced theoretical discussion with concrete credibility, effectively transforming South Africa’s world-leading platinum group metal reserves.
One of the more concerning themes was the absence of urgency around exploration. It wasn’t said directly, but it was implied. Exploration is not where the focus is right now and that may make sense today, but as we know in mining; today’s underinvestment becomes tomorrow’s constraint. And that is a long-term risk the industry should not ignore.
If I were to pinpoint what stood out to me, it would be how differently companies are positioning themselves:
- Focused PGM producers — disciplined, cash-driven, selective growth on existing assets.
- Integrated scale players — leveraging size, collaboration and consolidation.
- Diversified players — positioning into broader energy transition materials. Each strategy has merit, and each carries risk. Each carries risk.
One thing is certain, the PGM industry may no longer be in crisis, but it is not yet in full recovery. It sits somewhere in between. More confident than a year ago. More disciplined than the last upcycle. But still facing unresolved strategic questions.
The most important takeaway is this: The industry is starting to think again. Not just reacting — but thinking. We are considering capital, strategy and long-term positioning. And in mining, that is usually the first sign that a cycle is turning, the wheels of change are in motion.
The cycle doesn’t begin when prices move, it begins when mindsets shift.
~ Z. B. S.






















Latest Posts