
The EV Revolution Just Got Derailed… Here’s Who’s Laughing (Spoiler: It’s China)
The Raw Truth
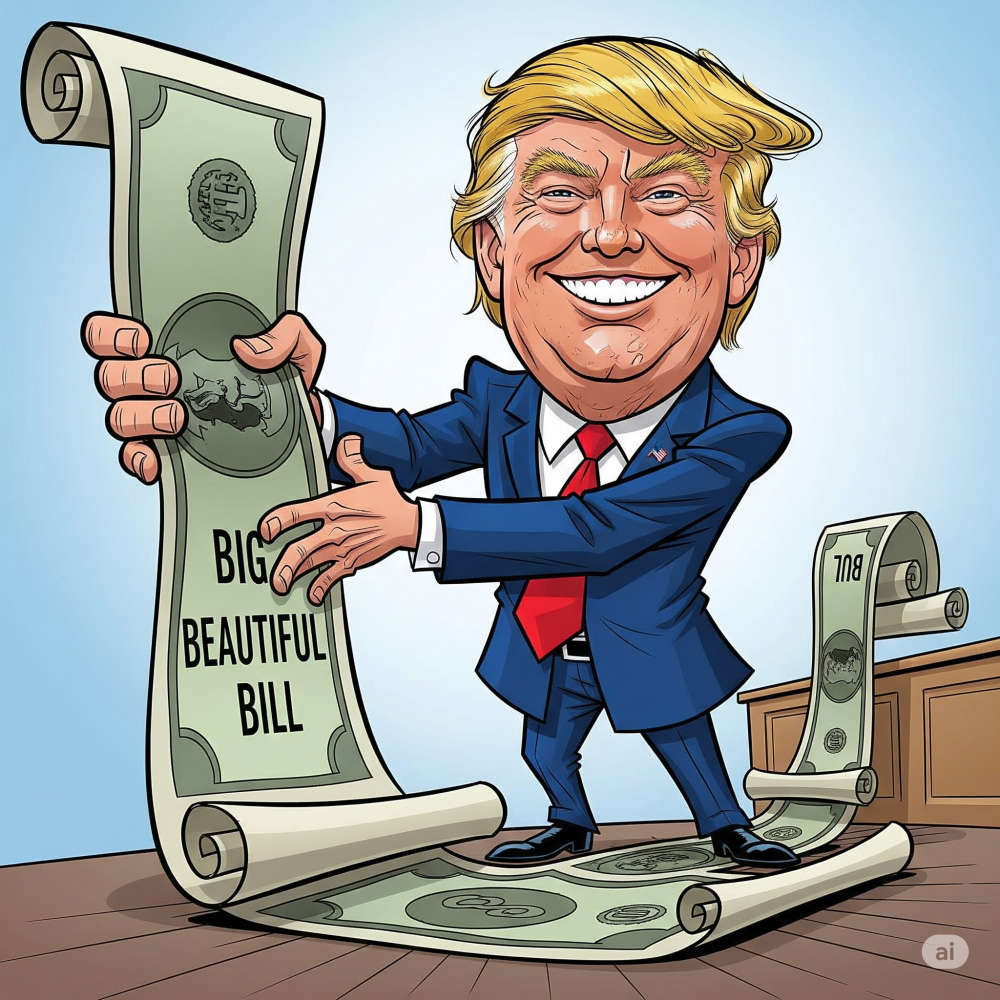
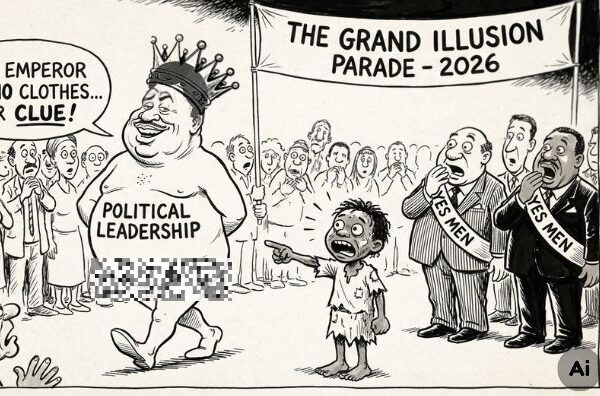
Like 99% of us (and the United States Congress and Senate Members), I haven’t read the +600 pages of this incoherent political diatribe. Let’s cut through the political noise. The so-called “One Big Beautiful Bill” isn’t just bad policy, it’s self-sabotage of America’s energy future in the longer term and caused critical damage to it’s renewable industry in the short term.
After the decades that I have spent in mining, this is one of the most short-sighted, ideologically driven attacks on U.S. industrial competitiveness I’ve ever seen.
(You wanted my opinion right). And I’ve lived through the Zuma and Zwane years of madness in South Africa.
Here’s what’s happening in a nutshell:
1. EV Tax Credits? Gone.
- The $7,500 incentive that made EVs affordable for middle-class buyers? Eliminated.
- Expect plummeting demand just as Ford, GM, and Tesla were scaling production – Great for PGM’s.
2. Battery Manufacturing Credits? Gutted.
- The IRA’s 45X credit for U.S.-made battery cells? Now being phased out.
- Translation: Gigafactories in Georgia, Tennessee, and Michigan just got less viable. How can you invest in an environment of fiscal and policy environment.
3. China Ban? More Like a China Gift.
- No credits if 40%+ of materials come from China? Great in theory.
- Reality: The U.S. (or for that matter, the rest of the world) has almost zero domestic supply of graphite, rare earths, and lithium processing. This isn’t a “ban”, it is a political lie, these minerals will continue to come from China, via some fronting arrangements, at much higher costs.
4. BESS Credits Expire in 2027.
- Battery storage projects just lost their financial backbone. (These are critical for renewables).
- Expect solar and wind farms to stall without affordable storage.
The Fallout: By the Numbers
- 440,000 jobs at risk (ICCT), many in red states that voted for this nonsense (you can envision that upside down smiling emoji here to capture how this makes me feel).
- $100B+ in private investment (since the IRA) is now in jeopardy.
- China’s EV dominance accelerates…they control 80% of battery supply chains.
- Luddites or is it Trumpites, taking sledgehammers to the technologies of the future.
Mining’s Double Whammy
I’ve said it before, many times and at many Indabas: You can’t have an energy transition without more mining. This bill proves Washington still doesn’t get it. But then, they don’t want an energy transition do they! Drill baby, drill!!
- Lithium: Projects like Thacker Pass (NV) and Piedmont Lithium (NC) relied on IRA stability. Now? Investors are spooked.
- Graphite: The U.S. produces ZERO battery-grade graphite. China supplies almost 100%. This bill does nothing to change that.
- Rare Earths: MP Materials’ California mine is the only U.S. source.
The US Department of defence funding this project directly and supporting the floor price is very smart!
Bottom line: This isn’t “America First.” It’s “America Stuck in an unsustainable past!”
China’s Victory
While the U.S. ties itself in knots, China is laughing all the way to the bank.
- They control most of the worlds refining capacity of critical minerals like: lithium, cobalt, rare earths, graphite, manganese, etc, etc.
- Their response? More subsidised funding, faster permits, and aggressive global mining deals (see: Ivory Coast, Congo, Bolivia, Indonesia).
My Unfiltered Take
This bill is a betrayal of American workers, miners, and manufacturers. It’s not just bad for EVs, it’s bad for energy security, jobs, and geopolitical leverage. It means one of the worlds largest economics is no longer.
Someone else’s shortsightedness may have unintended consequences far away in the ‘Shithole Country’ called South Africa.
The South Africa Angle
1. PGMs (Platinum Group Metals):
- Opportunity: With U.S. battery incentives shrinking, automakers may continue to delay EV rollout, but it may also impact negatively on hybrid uptake.
- Probably a net positive impact on PGM’s in the short-term
2. China’s Shadow:
- China is a great market for ore, but a monopolist when it comes to beneficiation.
- Manganese & Chrome: SA is a top producer, but our local ‘pit to Chinese port’ approach means we need improved logistics and affordable power.
3. Critical Minerals Wildcard:
- SA has untapped graphite, rare earths and other critical mineral reserves, but zero refining.
- Brutal Truth: Without creative and aggressive deals like the one just announced in the U.S. for MP Materials, China will lock up SA and Africas’s reserves for pennies.
Z.B’s Blunt Assessment
South Africa could be a winner in the future where minerals are required for clean energy and sustainable growth. But without clear policy and support it’s just another resource colony for China. President Ramaphosa needs to pay attention, or Johannesburg could become Beijing’s remote mining site.
As always, let’s debate in the comments!
Do you agree or disagree?
If you think I’m missing something, let me know! I read every response, and I appreciate the input!
P.S. Share this with someone who has influence. Maybe they’ll finally listen.
– Z.B.S

























Latest Posts